
Great question! This comes up very frequently. When you’re applying for a mortgage, most mortgage companies are going to require two years of stable job history explaining any job gaps from one job to another as well as doing a full two year history showing all dates of employment began and when employment ended during the full 24 months. If you change jobs, and you’re going from one industry to another industry you’re going to have to explain the change and why it took place and how your financial situation is battering because of the job change. As long as it’s just a job change from one W-2 position to another, you should be okay trying to qualify to buy a home or refinance a mortgage.
Where people get into trouble is when they switch jobs and their actual employment status changes that is going from being W-2 to going self-employed. This is an automatic 1 to 2 years timeframe it will take you to show income from being self-employed for the purposes of getting a mortgage. if you go from being self-employed to w2’ed, tenured and a venue to show either a pay stub and/or combination of the paystub and an offer letter showing what the income is going to be coupled with allowing the mortgage lender to do what’s called the verification of employment with your current employer. If you’d like to learn how potential job transfer or change might affect your ability to get a home loan, contact scott.sheldon@naf.com today!
Share:
Posted in:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
When You Should Rent and Not Buy a House
Buying a home can build long-term wealth, but not every buyer should purchase right now. Learn when renting may make more financial sense, including career changes, short moves, limited savings, high debt, and a stretched monthly budget.
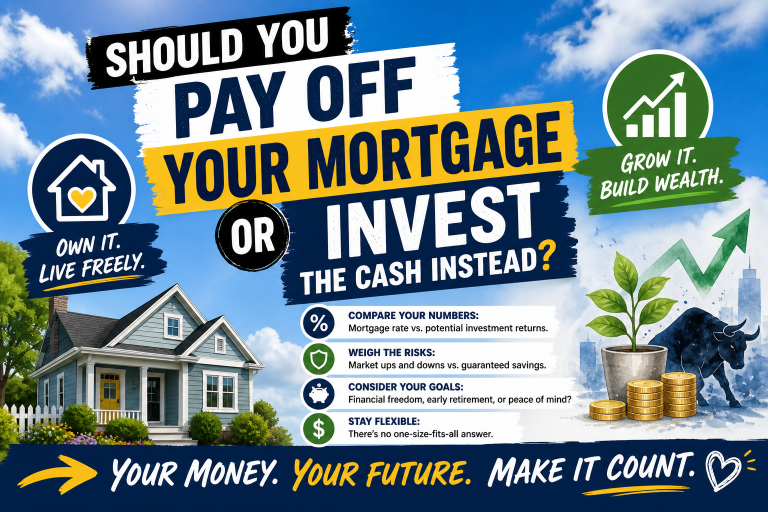
Should You Pay Off Your Mortgage or Invest the Cash Instead?
Paying off a mortgage offers guaranteed interest savings. Investing may offer growth, but it also brings risk. Here is how to weigh the decision.
Why Does My Mortgage Lender Keep Asking for the Same Documents?
Repeated mortgage document requests are frustrating, but they usually involve updated information, missing pages, or follow-up questions needed before closing.
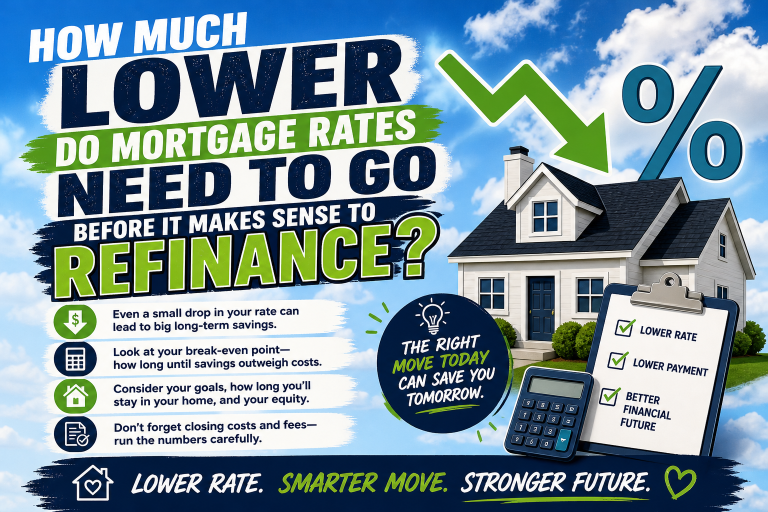
How Much Lower Do Mortgage Rates Need to Go Before It Makes Sense to Refinance?
A refinance is not about an arbitrary rate drop. Learn how loan size, costs, monthly savings, and break-even time determine whether it makes sense.
View More from The Mortgage Files:
1 Comment
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!
[…] your ability to pay (and therefore determining how much house you can afford), a lender will calculate your average income based on your pay from the past 24 months. It’s pretty straightforward if you’ve had the same […]