
Unfortunately no, lenders are under very tight scrutiny as our real estate appraisers to make sure there is no outside influence to inflate a property value for the purposes of securing a mortgage. The mortgage company you select a higher for financing is required to choose from a panel of appraisers, from there, they contact you directly to set up an inspection date. It doesn’t matter whether you’re buying a home or refinancing a property you already own, the process works in the same fashion.
How The Process Works
Consumer provides a credit card to the mortgage company, lender in turn provides this information to the appraisal company to charge in accordance with setting up the appraisal. The order is placed through the lender’s billing system and the order is set up to bid.
Once a local appraiser accepts the order, they receive the contact information for the borrower and they subsequently contact that person to set up an inspection date. No longer can you write the appraiser check directly to an appraiser. In some occurrences when purchasing a home the appraiser might be instructed to contact either the buyer’s agent or the listing agent depending on preferences. However, appraiser is under no obligation to contact the agent to inspect the property especially the property has an MLS lockbox key.
Plan on approximately $450 for a home appraisal.
Want to start a new mortgage loan with a guaranteed local appraiser? Contact ScottS@snmc.com today!
Share:
Posted in:
RELATED MORTGAGE ADVICE FROM SCOTT SHELDON
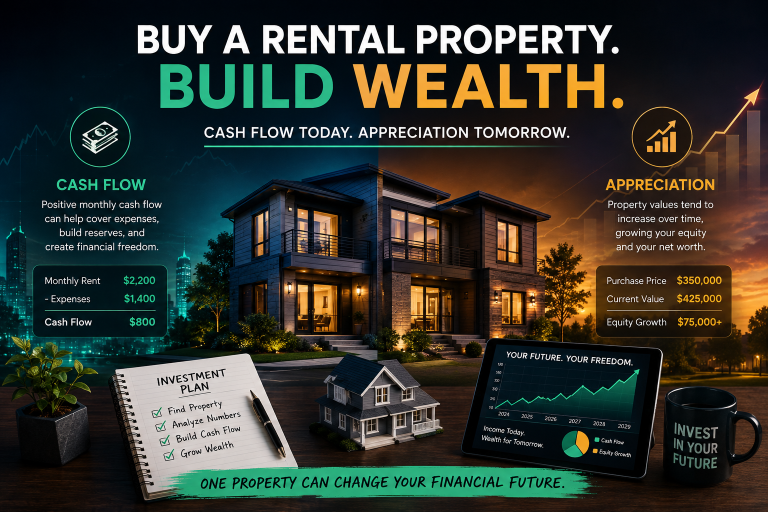
Should You Buy a Rental Property for Cash Flow or Appreciation?
Cash flow and appreciation can both build wealth through rental real estate, but they work differently. Learn how to balance income, equity, financing, and tax planning.
New Fannie Mae Departing Residence Rental Income Rules: What Homebuyers Need to Know
Fannie Mae’s 2026 departing-residence update changes how rental income may be documented when you keep your current home as a rental and buy another primary residence.
How to Buy a Home With a Financed Down Payment
A financed down payment program may help qualified buyers purchase with little or no down payment. Learn the payment tradeoffs and who it may fit.
Income, Credit, and Down Payment: How Mortgage Approval Really Works
Mortgage approval is about more than a credit score. Learn how income, debt, credit, and down payment work together when buying a home.
View More from The Mortgage Files:
begin your mortgage journey with sonoma county mortgages
Let us make your mortgage experience easy. Trust our expertise to get you your best mortgage rate. Click below to start turning your home dreams into reality today!